

Contents:
This Week’s Key Economic Data and Events.
Charts and Key Levels to Watch
Continued warning signs from high-yield bonds
Pass/Fail Screen for AI Universe.
The Week Ahead
As a reminder, the bond market is closed today for Columbus Day (Indigenous Peoples’ Day).
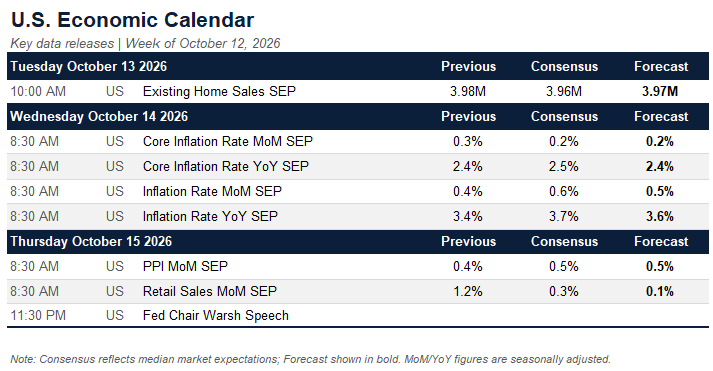
This week’s big event will be Wednesday’s inflation data release. This may provide more clarity on what the Fed will do at the end of this month during its FOMC meeting.
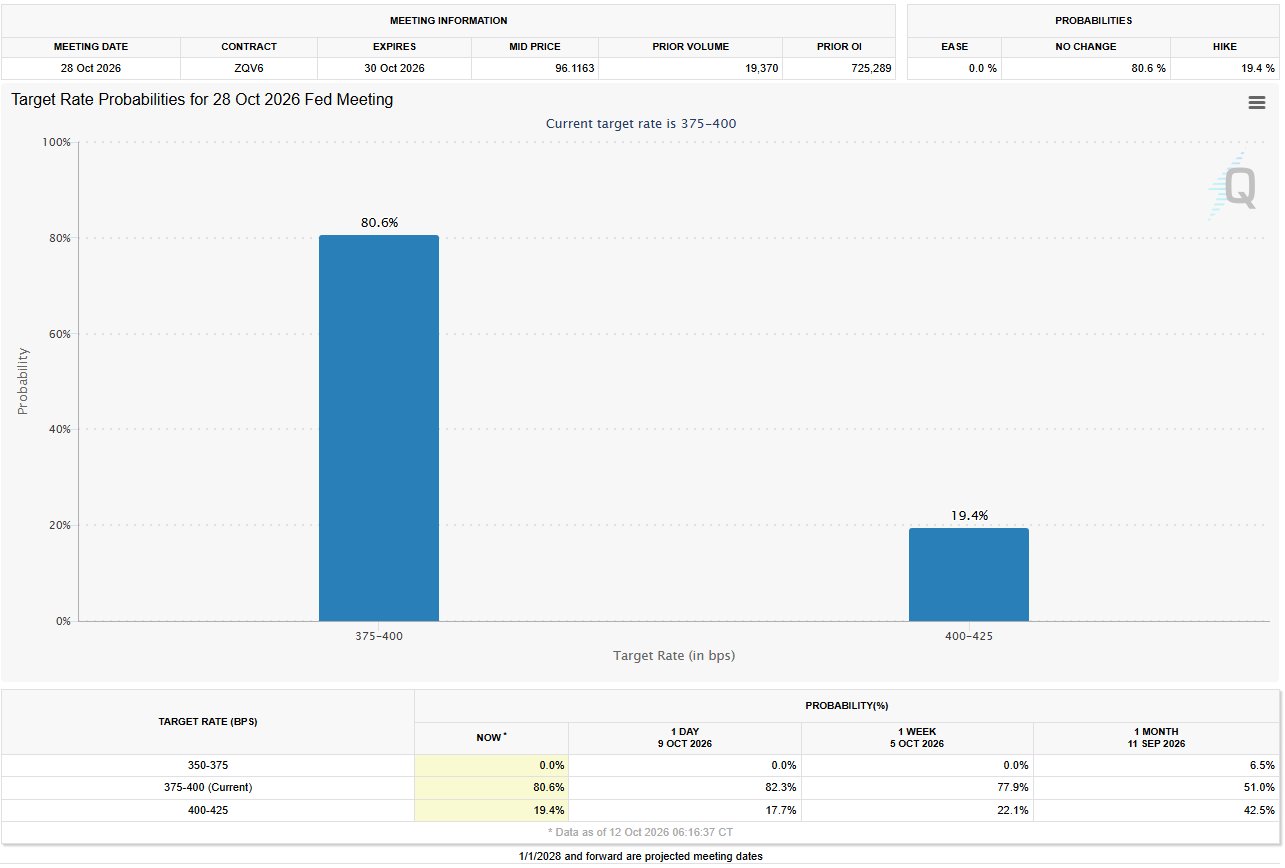
The current debate is focused on whether the Fed will/should raise rates right before the midterm election. Currently, the CME’s FedWatch tool (which is based on the 30-Day Fed Funds Futures) is predicting an 80% chance that the Fed does nothing:
In addition, some key earnings reports are being released by companies in the Financials sector, and (more importantly) Taiwan Semiconductor.
Taiwan Semiconductor (TSM) plays an important part in the AI supply chain as the company is the world’s largest semiconductor foundry and supplies companies like Nvidia, Apple, Broadcom, Qualcomm, AMD, Intel, and Amazon (AWS).
TSM’s earnings report will test the market’s appetite for AI stocks - especially after last week’s worries about circular AI spending and OpenAI’s weaker-than-expected revenue announcement.
Charts and Key Levels to Watch This Week:
The overall market trend is still intact:
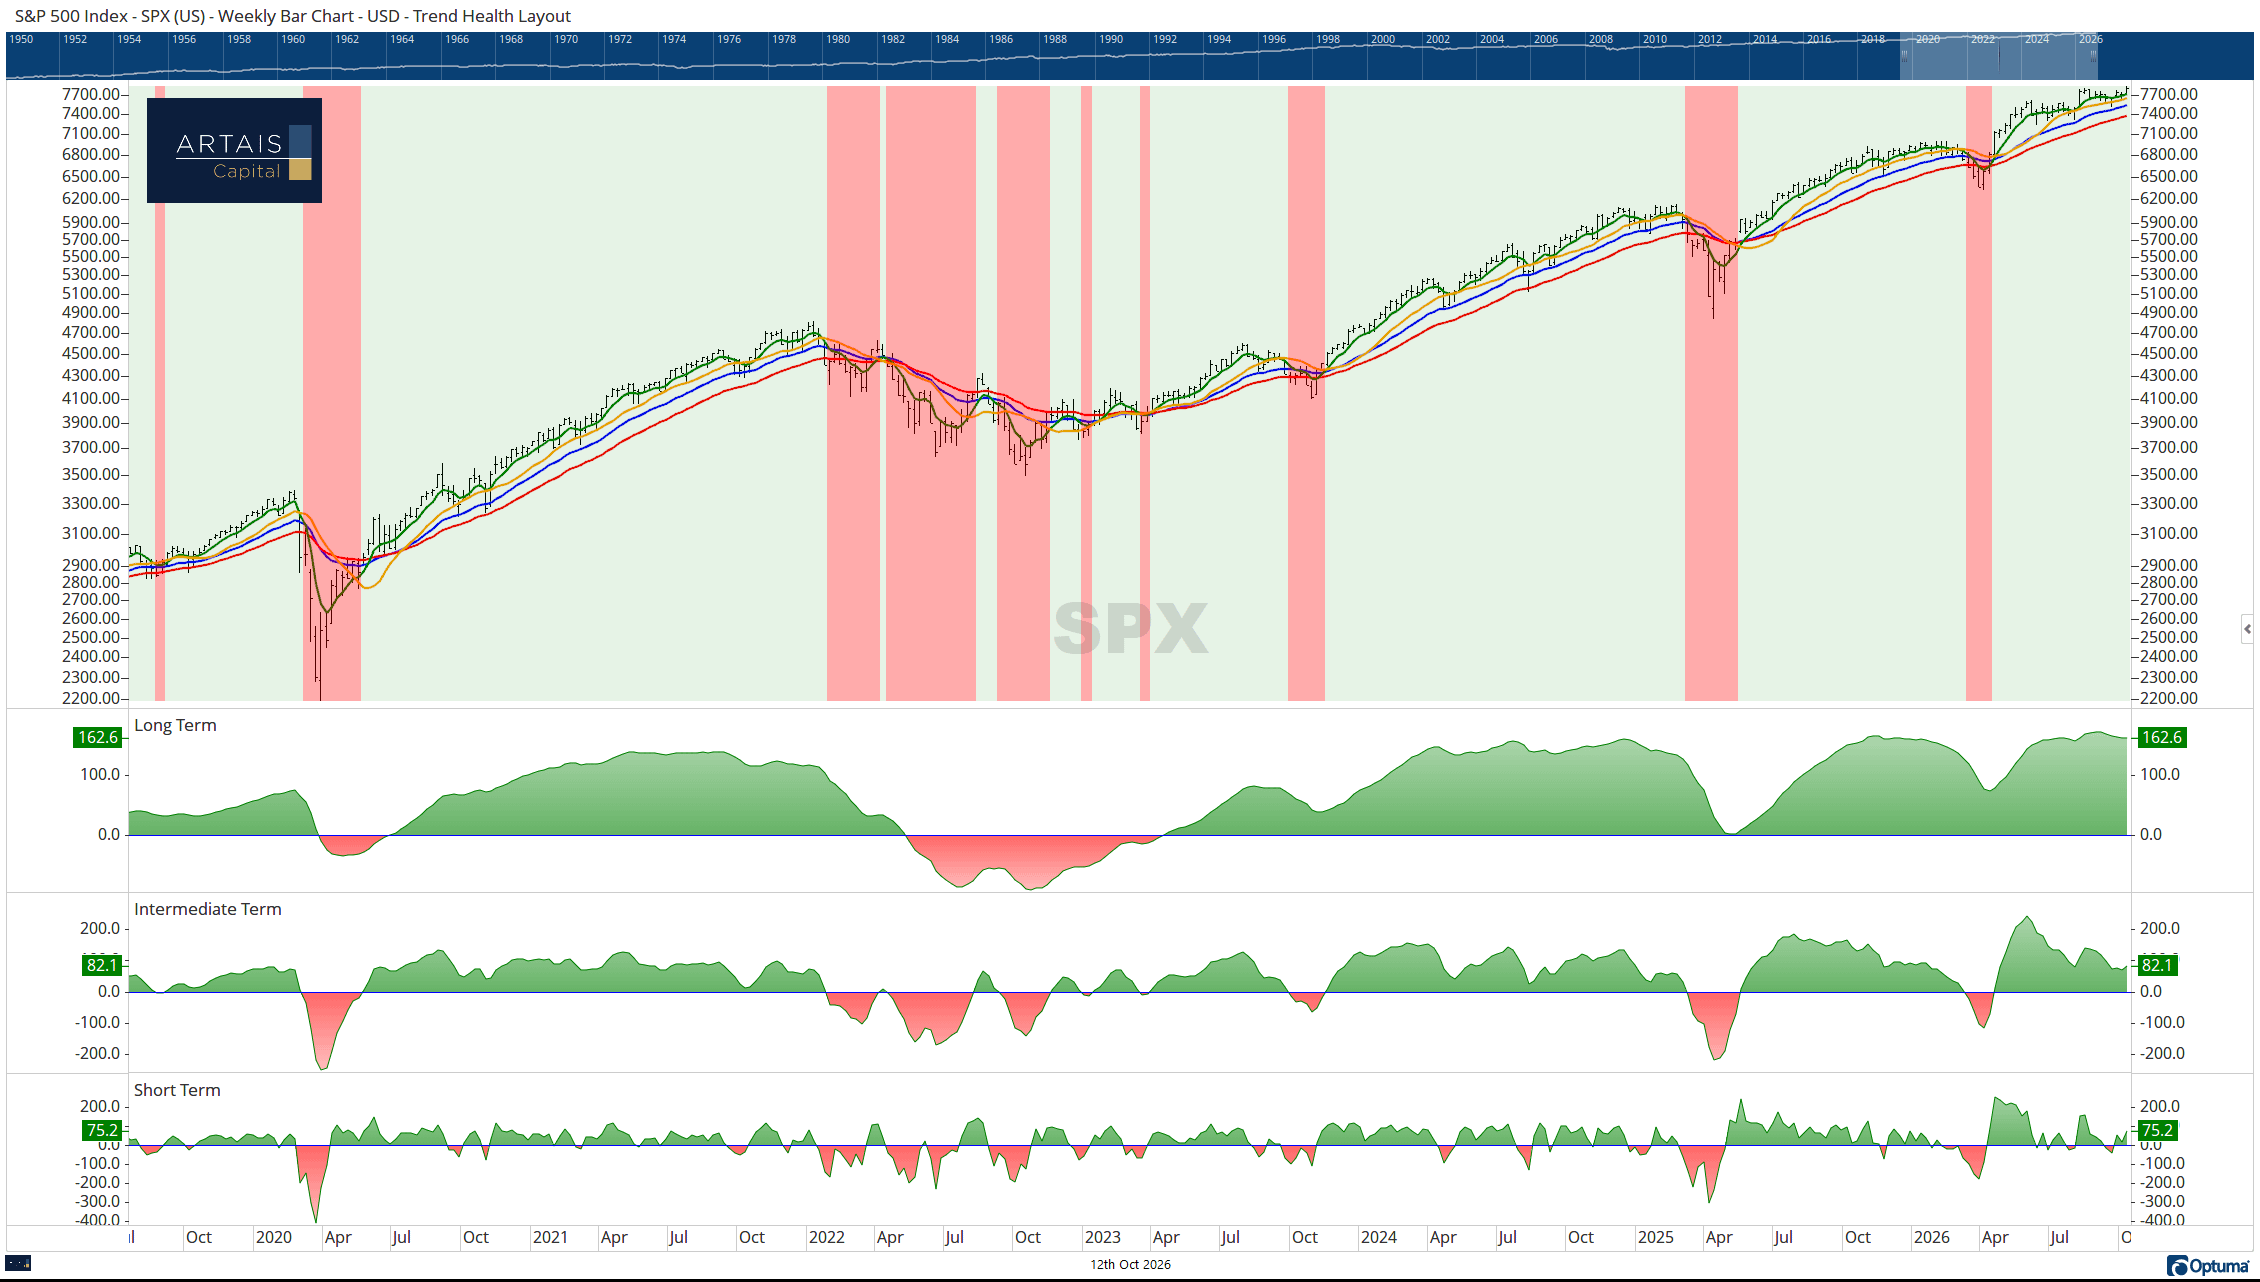
Short, intermediate, and long-term trends are still intact
But there is some rotation away from the technology (XLK) sector and into value sectors, like utilities (XLU):
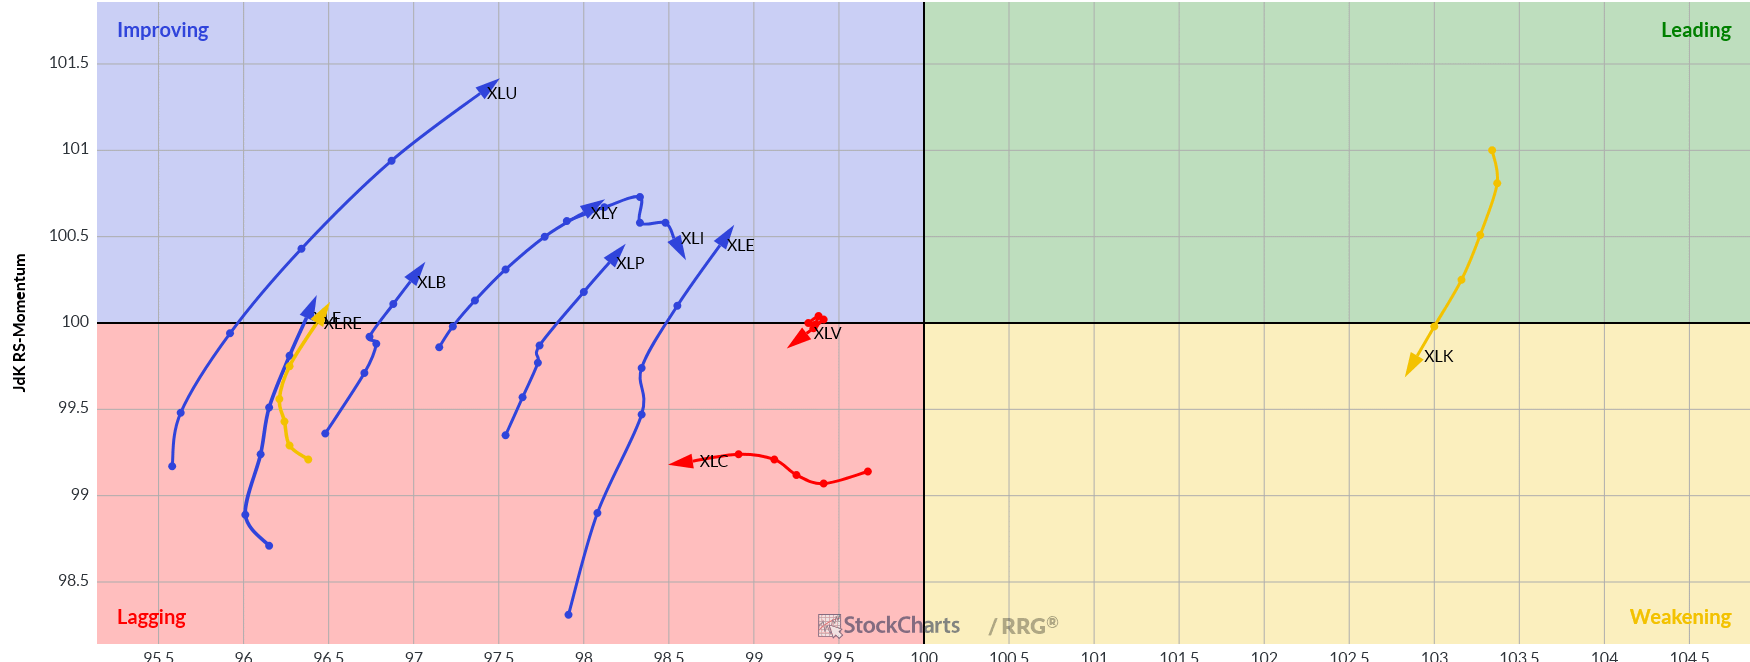
Relative Rotation graph (RRG) showing momentum and relative strength of the 11 sectors in the S&P 500 index vs the index itself
What concerns me about this rotation is that we are entering a time frame that is historically very good for stocks, but the market is doing the opposite of what one would expect.